(888) 979-7969
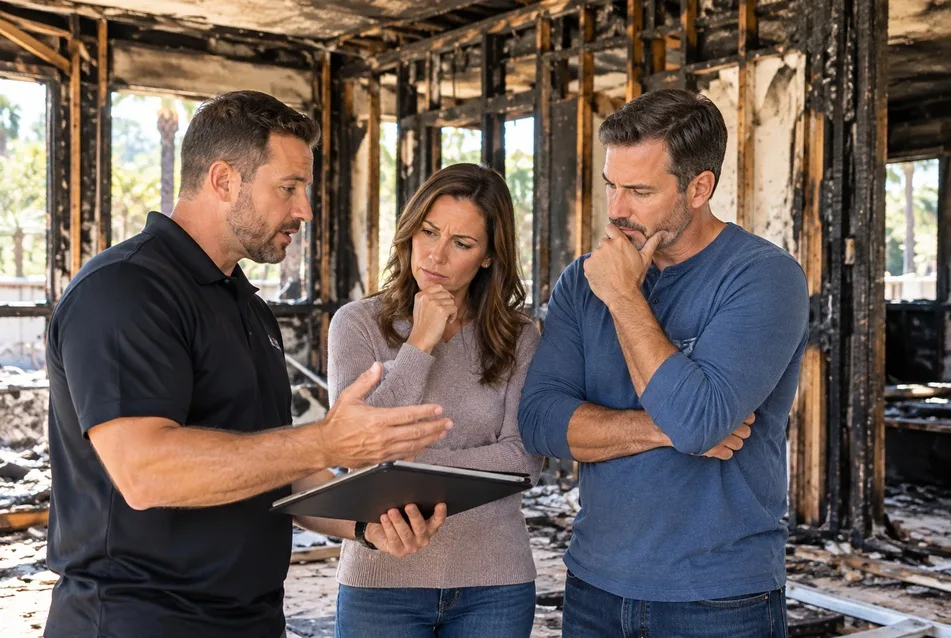
After a house fire, a public insurance claims adjuster works for you, not your insurance company. They document every part of the loss, including smoke, soot, and hidden structural damage that is easy to miss, build a detailed estimate, and negotiate with the carrier so your settlement reflects what it will really cost to put your home and life back together.
A fire leaves you dealing with shock, displacement, and a claim process that can feel stacked against you. You do not have to handle it alone. At Ultra Property Damage, we stand on the homeowner's side from the first call. For a free claim review, contact our team at (888) 979-7969.
What fire damage do insurers undervalue without a public insurance claims adjuster?
Insurers often undervalue smoke and soot damage, water damage from firefighting, and structural damage that is not obvious at first glance. The burned rooms get the attention, while the damage spread through the rest of the house gets overlooked.
Smoke travels far beyond the flames. It works its way into HVAC ducts, attic insulation, closets, drawers, and the inside of cabinets. Soot is acidic and can stain and corrode surfaces over time, and the odor can linger in drywall and fabrics long after the visible mess is cleaned. Then there is the water. When Orlando Fire Department or Orange County Fire Rescue crews put out a fire, a large volume of water can soak floors, walls, and subfloors, setting up the conditions for mold in Central Florida's humidity.
Structural damage can hide behind the walls. Heat can weaken roof trusses, wiring, and framing in rooms that look fine. In older homes around College Park and Thornton Park, original materials and decades of renovations can make the true scope even harder to see. A thorough inspection catches what a quick walkthrough misses.
Why does the insurance company's adjuster work for the insurer?
The adjuster your insurance company sends is employed or hired by the carrier. Their job is to evaluate the claim on the company's behalf, which means the company's interests come first, even when the adjuster is polite and professional.
That is not a personal criticism. It is simply how the system is built. Carrier adjusters often handle heavy caseloads and work from standardized pricing and the carrier's view of the policy. Items get missed, depreciated, or left off the estimate, and homeowners in the middle of a crisis rarely know what to question.
A licensed public adjuster balances that relationship. They read your policy, inspect the property, prepare an independent estimate, and handle the back and forth with the insurer. Our public adjusting services put a trained advocate on your side of the table, so you are not negotiating against professionals by yourself while you are trying to find a place to stay.
How do documentation and scope affect the size of your fire damage payout?
Your payout is based on the documented scope of the loss. If damage is not documented and included in the estimate, it usually does not get paid. Detailed records are the foundation of a fair settlement.
Scope means every item of work needed to restore the home: demolition, smoke and soot cleaning, odor treatment, drying, structural repairs, rebuilding, and replacement of damaged belongings. The more complete and specific that scope, the stronger your position in negotiations. Photos, videos, room by room inventories, and expert reports all support it.
We worked with an Orlando homeowner who had photographed the burned rooms after her house fire. What she had missed were details like the soot inside her cabinets and the smoke damage that had ruined her clothing. With our help, she documented all of it, which gave her what she needed to negotiate effectively with the insurer. Small details like those add up quickly across a whole house.
What are the first steps to take after a house fire in Orlando?
Make sure everyone is safe, get the fire report, notify your insurance company promptly, and protect the property from further damage. Then start documenting everything before any cleanup begins.
Request a copy of the fire report from the responding fire department. Notify your insurer as soon as possible, since policies and Florida law set deadlines for reporting a claim. Keep receipts for hotels, meals, and other extra costs, because many policies cover additional living expenses. Take wide photos and close-ups of every room, including areas that look untouched. Avoid throwing anything away before it has been documented.
Emergency steps like boarding up openings and tarping the roof help prevent further damage, and our insurance restoration support can help coordinate that work with your claim. Do not sign a settlement or a contract you do not understand.
Facing a fire loss and unsure where to start? Call Ultra Property Damage at (888) 979-7969, or request your free claim review, and let a public insurance claims adjuster fight for the settlement you deserve.